All Categories
Featured
Strategies for Lowering Premiums With Chronic Conditions

Empathy-Driven Risk Assessment for High-Risk Applicants
How to Secure 2026 Impaired Risk Life Insurance
Table of Contents
A pre-existing health condition does not indicate you can't receive a life insurance policy, but it just impacts your offered choices and rates. Severe conditions such as cancer or a past cardiac arrest might position you in a higher-risk category, many people presume that they don't certify for coverage.
You still have options and that's when impaired threat life insurance comes into the image. Remember: You can get life insurance protection with a medical condition.
Whether you have medical or non-medical high-risk factors, you still likely have alternatives. The key is to match the policy alternatives to your objectives and current monetary or individual scenarios. In case of impaired conditions, getting coverage is simpler through no-medical-exam choices that may be much easier to certify for than totally underwritten term or long-term life insurance policies.
It is a convenient option for those with vital health concerns seeking ensured approval however at a greater premium and lower protection amount.
The costs are often lower than guaranteed concern policies but higher than conventional totally underwritten policy types. Term life insurance deals coverage for a set period of 10-40 years that stays the very same throughout the policy's term. It can be an ideal alternative for those seeking inexpensive protection for momentary requirements and covering major financial obligations.
Integrating Life Insurance with Special Needs Trust Planning
Whole life insurance offers lifelong coverage with money value accumulation. It typically comes at a greater cost and those with reasonably steady health conditions who do not mind going through a medical test might unlock greater protection. Specific variations like last expenditure insurance might be appropriate for covering smaller protection needs. Not all insurers may use comparable coverage alternatives and ensured problem is not your only alternative. Various insurers might assess danger in a different way, so always compare quotes.
Timing matters, so wait if your condition is enhancing to certify for much better options later. Don't use with too lots of insurance providers at the very same time. Be honest and transparent in your application to avoid claim rejections later on. Even as an impaired-risk applicant, you might still have the ability to get coverage.
Here are some pointers you may follow: Make sure that your condition is well handled and you follow the treatment plan. Avoid using immediately after a condition is detected.
Download and complete any appropriate questionnaires suggested based off the preliminary questionnaire.
Specialized Coverage for Cancer Survivors
Life insurance coverage can be complicated, particularly when it comes to underwriting. This post looks for to clarify life insurance coverage underwriting by presenting clear, accurate info to assist you make informed choices.
A lot of business now provide quick underwriting options, which permit you to reduce the time essential to get guaranteed. This indicates you might get protection the fastest method without jeopardizing on thoroughness in its appraisal. Stay ahead of the market with unique feature stories on the leading business, expert insights and the latest news provided straight to your inbox.
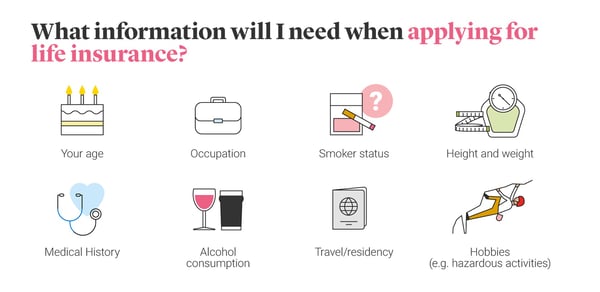
While it holds true that health plays a large function in underwriting, insurance providers consider lots of aspects, consisting of age, lifestyle, and household medical history. Even if you have some health problems, you can still find competitive rates customized to your situation. It's everything about discovering the right policy that matches your requirements and circumstances.
Each policy type, the amount of protection you desire, and the scrutiny will depend on it. For lots of policies, especially those with lower protection quantities, the process can be simple and does not require much time. Some even provide no-exam policies, which count on existing medical records and other data and make determinations based on that.
Insurance providers are keen to use cover to as many individuals as possible. To this end, they should make sure that these premiums will be based on the level of the threat. Precise assessment of one's risk will allow underwriters to offer a policy that protects one at a fair cost.
How to Secure Impaired Risk Insurance
When you're taking a look at life insurance coverage alternatives, you'll likely desire the best value for the very best rate. Medical underwriting is one aspect that may impact what you pay for your life insurance premium. It involves your health and household case history and can increase or reduce your payments. Let's have a look at how medical life insurance coverage underwriting can impact your policy.
In the case of health insurance, the much healthier you are, the less you'll probably have to pay for your premium. Medical underwriting is a comparable procedure for life insurance coverage.
1 The insurer takes a look at medical history, lifestyle routines, demographics, and other aspects related to medical needs. After an insurance provider collects medical info, an insurance business will utilize statistical analysis to figure out the applicant's rate class and make a recommendation that best fits their situation.
Medical underwriting3 is simply one part of the whole life insurance underwriting procedure. Life insurance coverage business typically also take a look at financial status, such as earnings or insolvency history, during the life insurance coverage underwriting procedure. These elements help an insurer offer the finest rate based upon your special monetary situation.
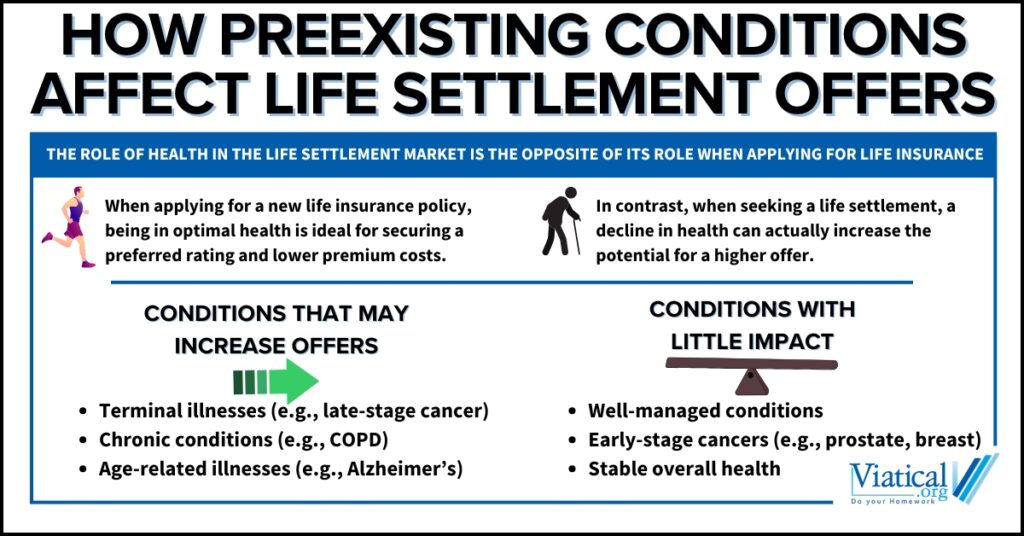
Without verification that medical history and other factors involving life insurance do not present a threat, a life insurance coverage company might charge a higher premium to remain protected. Depending on how high of a risk an insurance company figures out a candidate to be, a premium might be lower or higher than average.
Integrating Insurance with Special Needs Planning
In some cases, like when medical underwriting is not a requirement, life insurance coverage underwriting may be completed in as little as 24 hours. The length of the medical underwriting procedure for life insurance coverage differs.

Latest Posts

Smart Strategies for International Medical Coverage
How to Secure 2026 Impaired Risk Life Insurance

Strategies for Lowering Premiums With Chronic Conditions