All Categories
Featured

Life Insurance for HIV Status Applicants
Table of Contents
With these policies, you might still need to submit a diabetes-related questionnaire and grant consent for the life insurance coverage business to request your health records. The premiums are higher, however they may enable you to get protection you would not be able to get approved for with a medical examination.
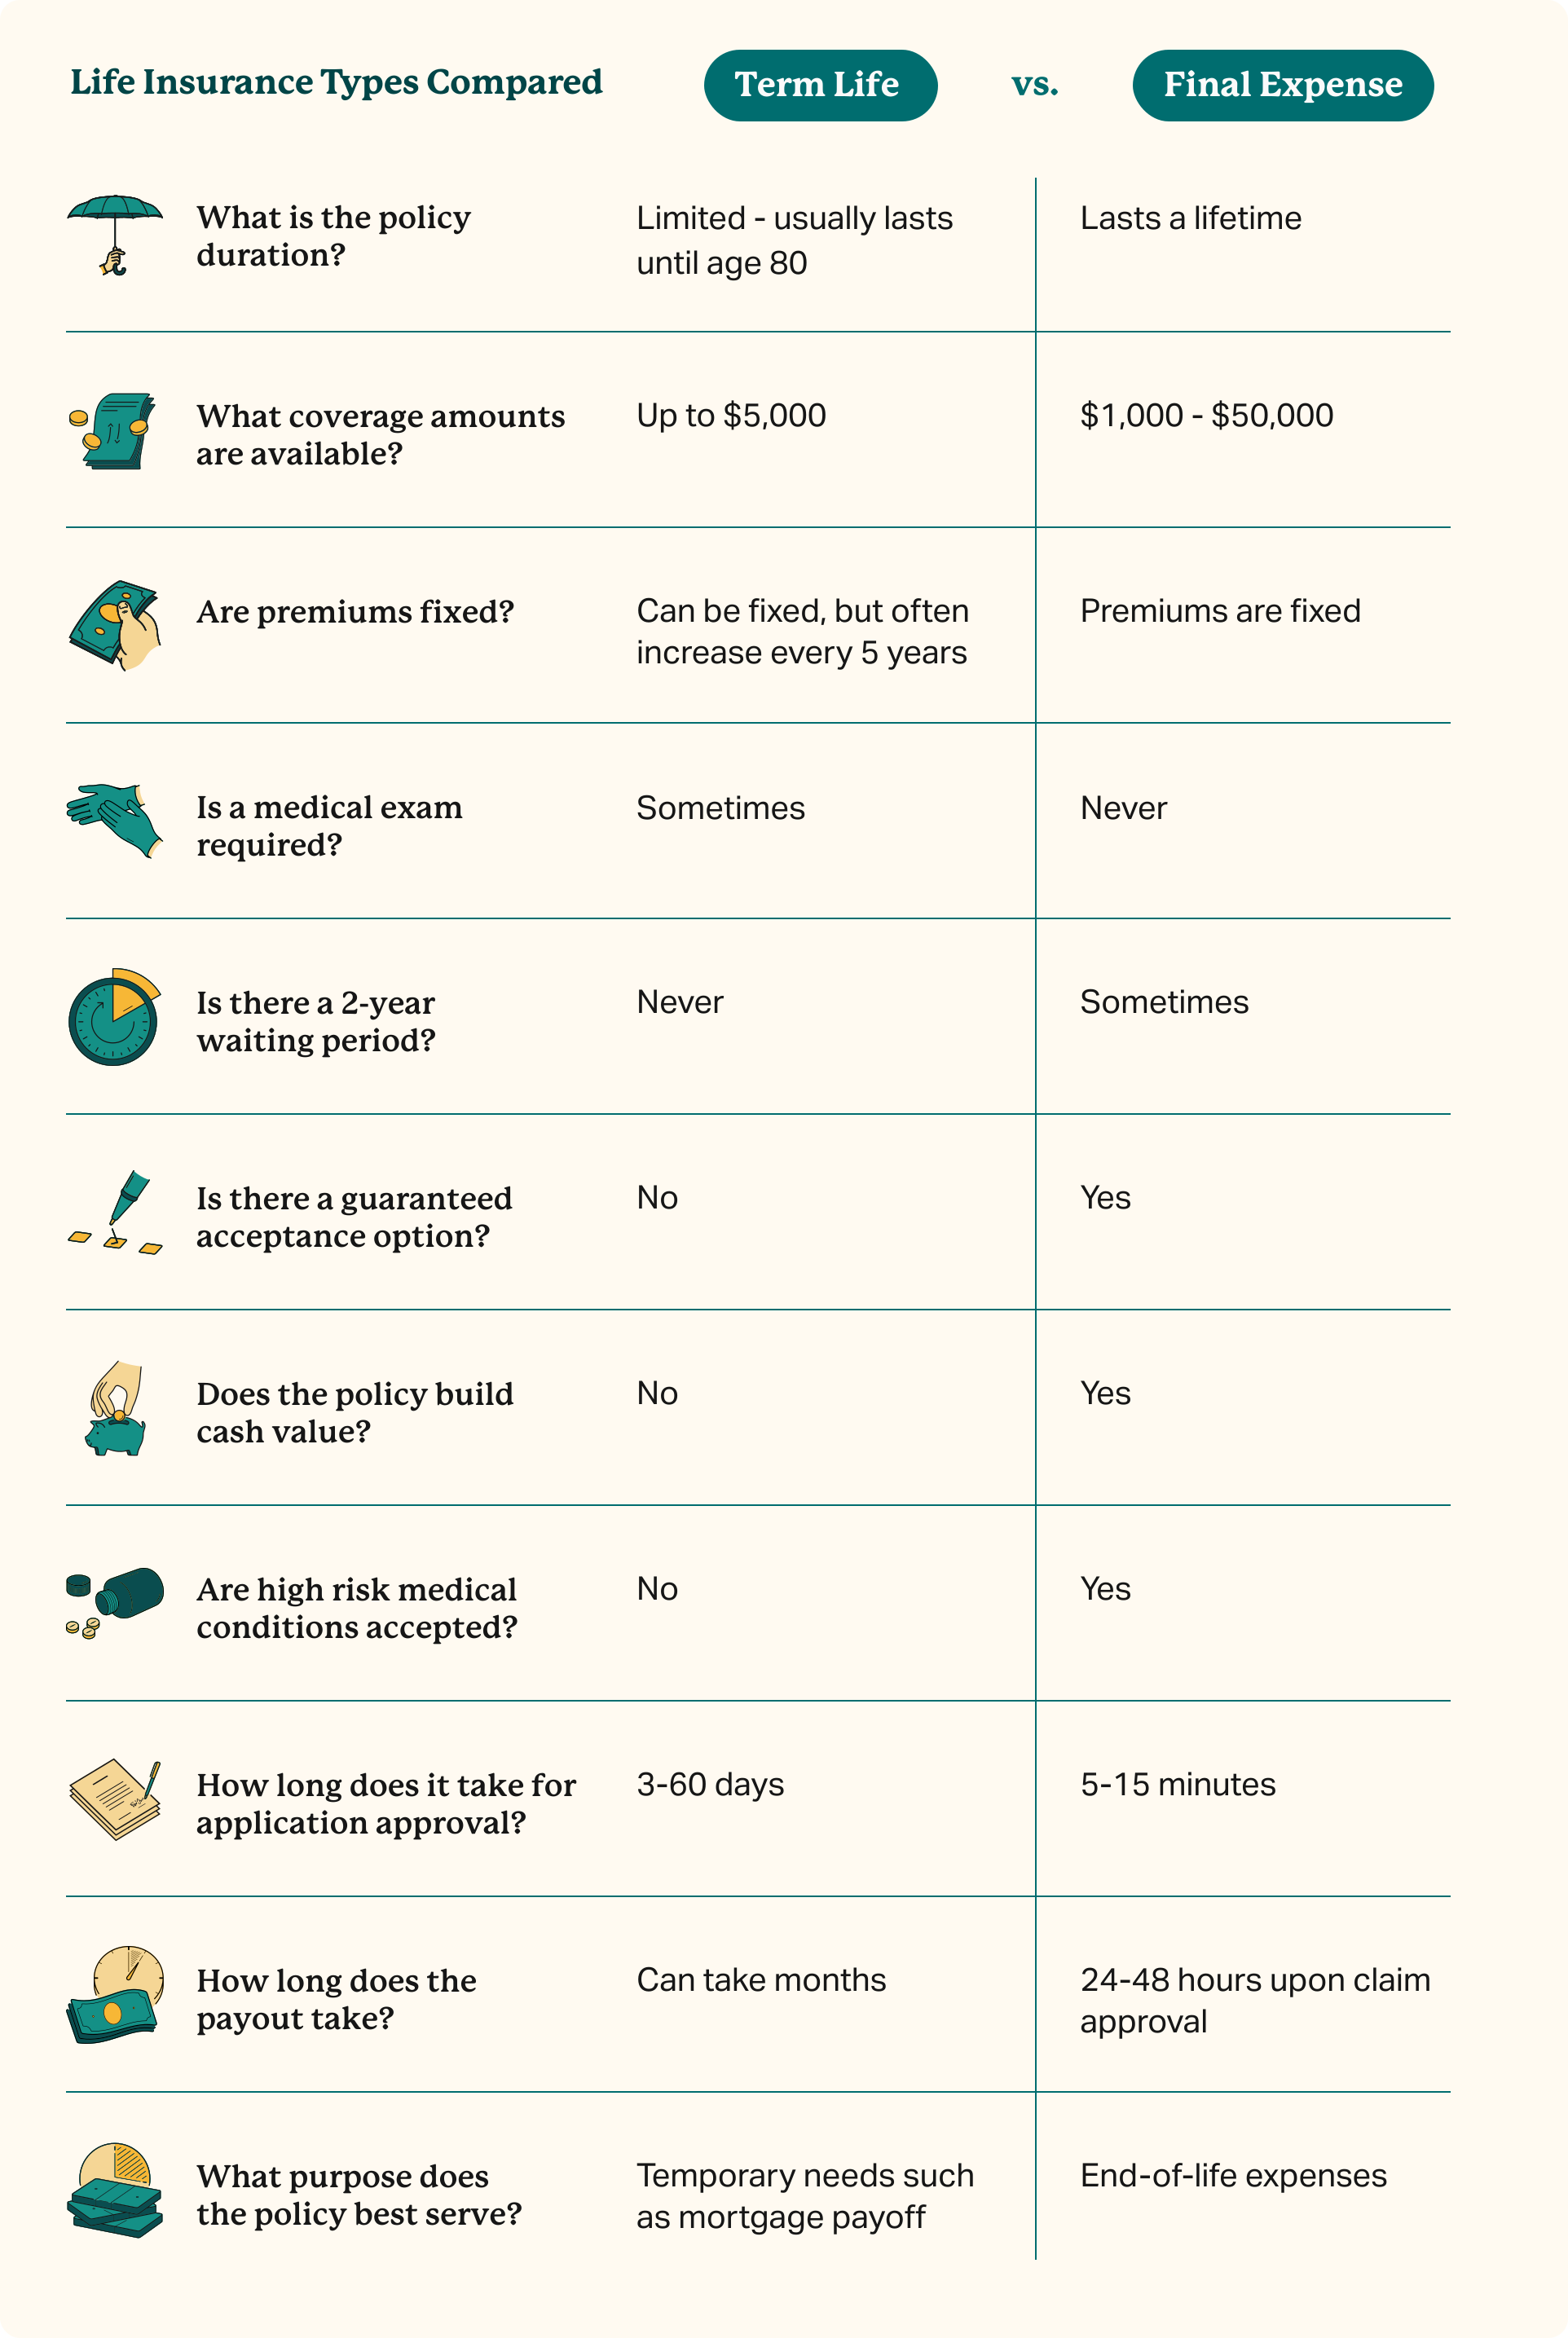
There is a possibility you may not be considered for coverage, even with a no-medical-exam insurance plan, due to your diabetes. In this case, a guaranteed-issue "last expenditure" policy might still be an option, although a number of the top life insurance coverage companies don't offer them. Surefire issue life insurance is available without medical exams or health questions, making it available for people with severe health conditions.
These insurance plan might only permit a maximum survivor benefit of $25,000 or less, and they frequently have a waiting duration that can be as long as 2 to 3 years. That means if you were to pass away before the waiting duration was up, your recipients would not receive the full survivor benefit.
Ways Cancer Survivors Can Secure Affordable Life Coverage
Finding the finest life insurance for diabetics typically involves comparing policy features and seeking personalized recommendations to ensure the policy satisfies private needs at an appropriate expense. Know that while getting life insurance coverage as a diabetic may need extra actions, there are options offered that might assist you get coverage.
This will likely be your most budget-friendly option, although you may just certify for a minimal coverage quantity. Make sure to speak frankly with your representative and let them understand about your diabetes so that they can promote on your behalf.
Broaden all Diabetes is thought about a pre-existing condition by insurance companies, which can impact eligibility and rates. Diabetics can and do get life insurance policies every day. Notably, the kind of life insurance coverage and the cost will depend, in part, on the type of diabetes you have and whether you are preserving a healthy lifestyle that helps you manage your blood glucose levels and signs.
Life Insurance Critical Illness RiderDiabetes will affect the policy rates, but not always by the very same amount. Type 2 diabetes is generally thought about less of a danger than Type 1 diabetes, specifically if you are detected at an older age and can control it with diet and workout. The best response is to talk with an insurance coverage professional about your specific scenario.
Life Insurance Critical Illness Rider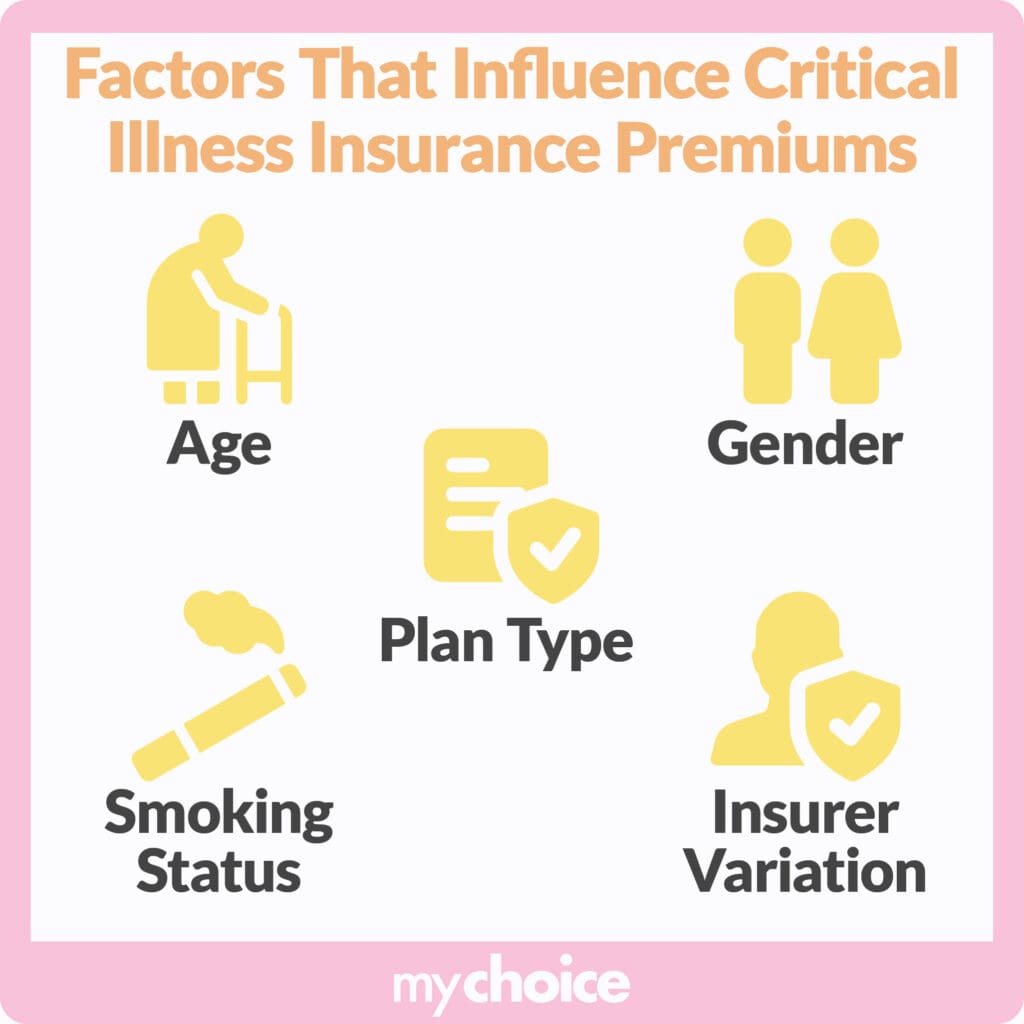
Effective Policy Strategies for Special Needs Trusts
All insurance requirements are different. Diabetic life insurance coverage premiums may be higher, however some aspects can mitigate the expense effect, such as the length of time the person has had diabetes, how well-controlled it is, and any medical examination results. In any case, a term policy will offer diabetics more economical life insurance coverage protection with a larger survivor benefit compared to a long-term policy, such as entire life insurance coverage.
Life insurance coverage applications ask questions about your health, and the process normally needs you to offer the insurance provider approval to access any health records required to confirm your details. In addition, you will generally require to have a medical examination as part of the underwriting procedure. They will search for specific markers in your blood work and other tests that suggest an underlying medical condition whether you know that condition or not.
Individuals and families can purchase health insurance through a Health Insurance Market (Marketplace) offered in every state. Beginning in 2014, all brand-new medical insurance plans, whether offered inside or outside the Marketplace, can not reject protection, charge more, or refuse to cover treatments due to the fact that you or somebody in your family has diabetes.
A Health Insurance Coverage Marketplace is a method for people, families, and small services to go shopping forand comparevarious personal health insurance coverage choices all in one location. Strategies used in the Marketplace needs to meet particular requirements for benefits, customer securities, and cost to the consumer. Marketplace strategies are separated into 4 different categories: Bronze, Silver, Gold, and Platinum.
In basic, moving from Bronze to Platinum, out of pocket expenses get lower while premiums tend to get greater. Typically, anyone who buys health insurance on their own can buy it through a Marketplace. However, only those who meet particular earnings requirementsand who do not receive inexpensive job-based health protection or certain other kinds of coverageare able to get monetary help paying for a strategy bought in the Marketplace.

Latest Posts
Securing Financial Stability for Vulnerable Family
2026 Life Policies for Diabetic Case Profiles
Upcoming Trends in High Risk Insurance Approaches